Aspect
Risk Management
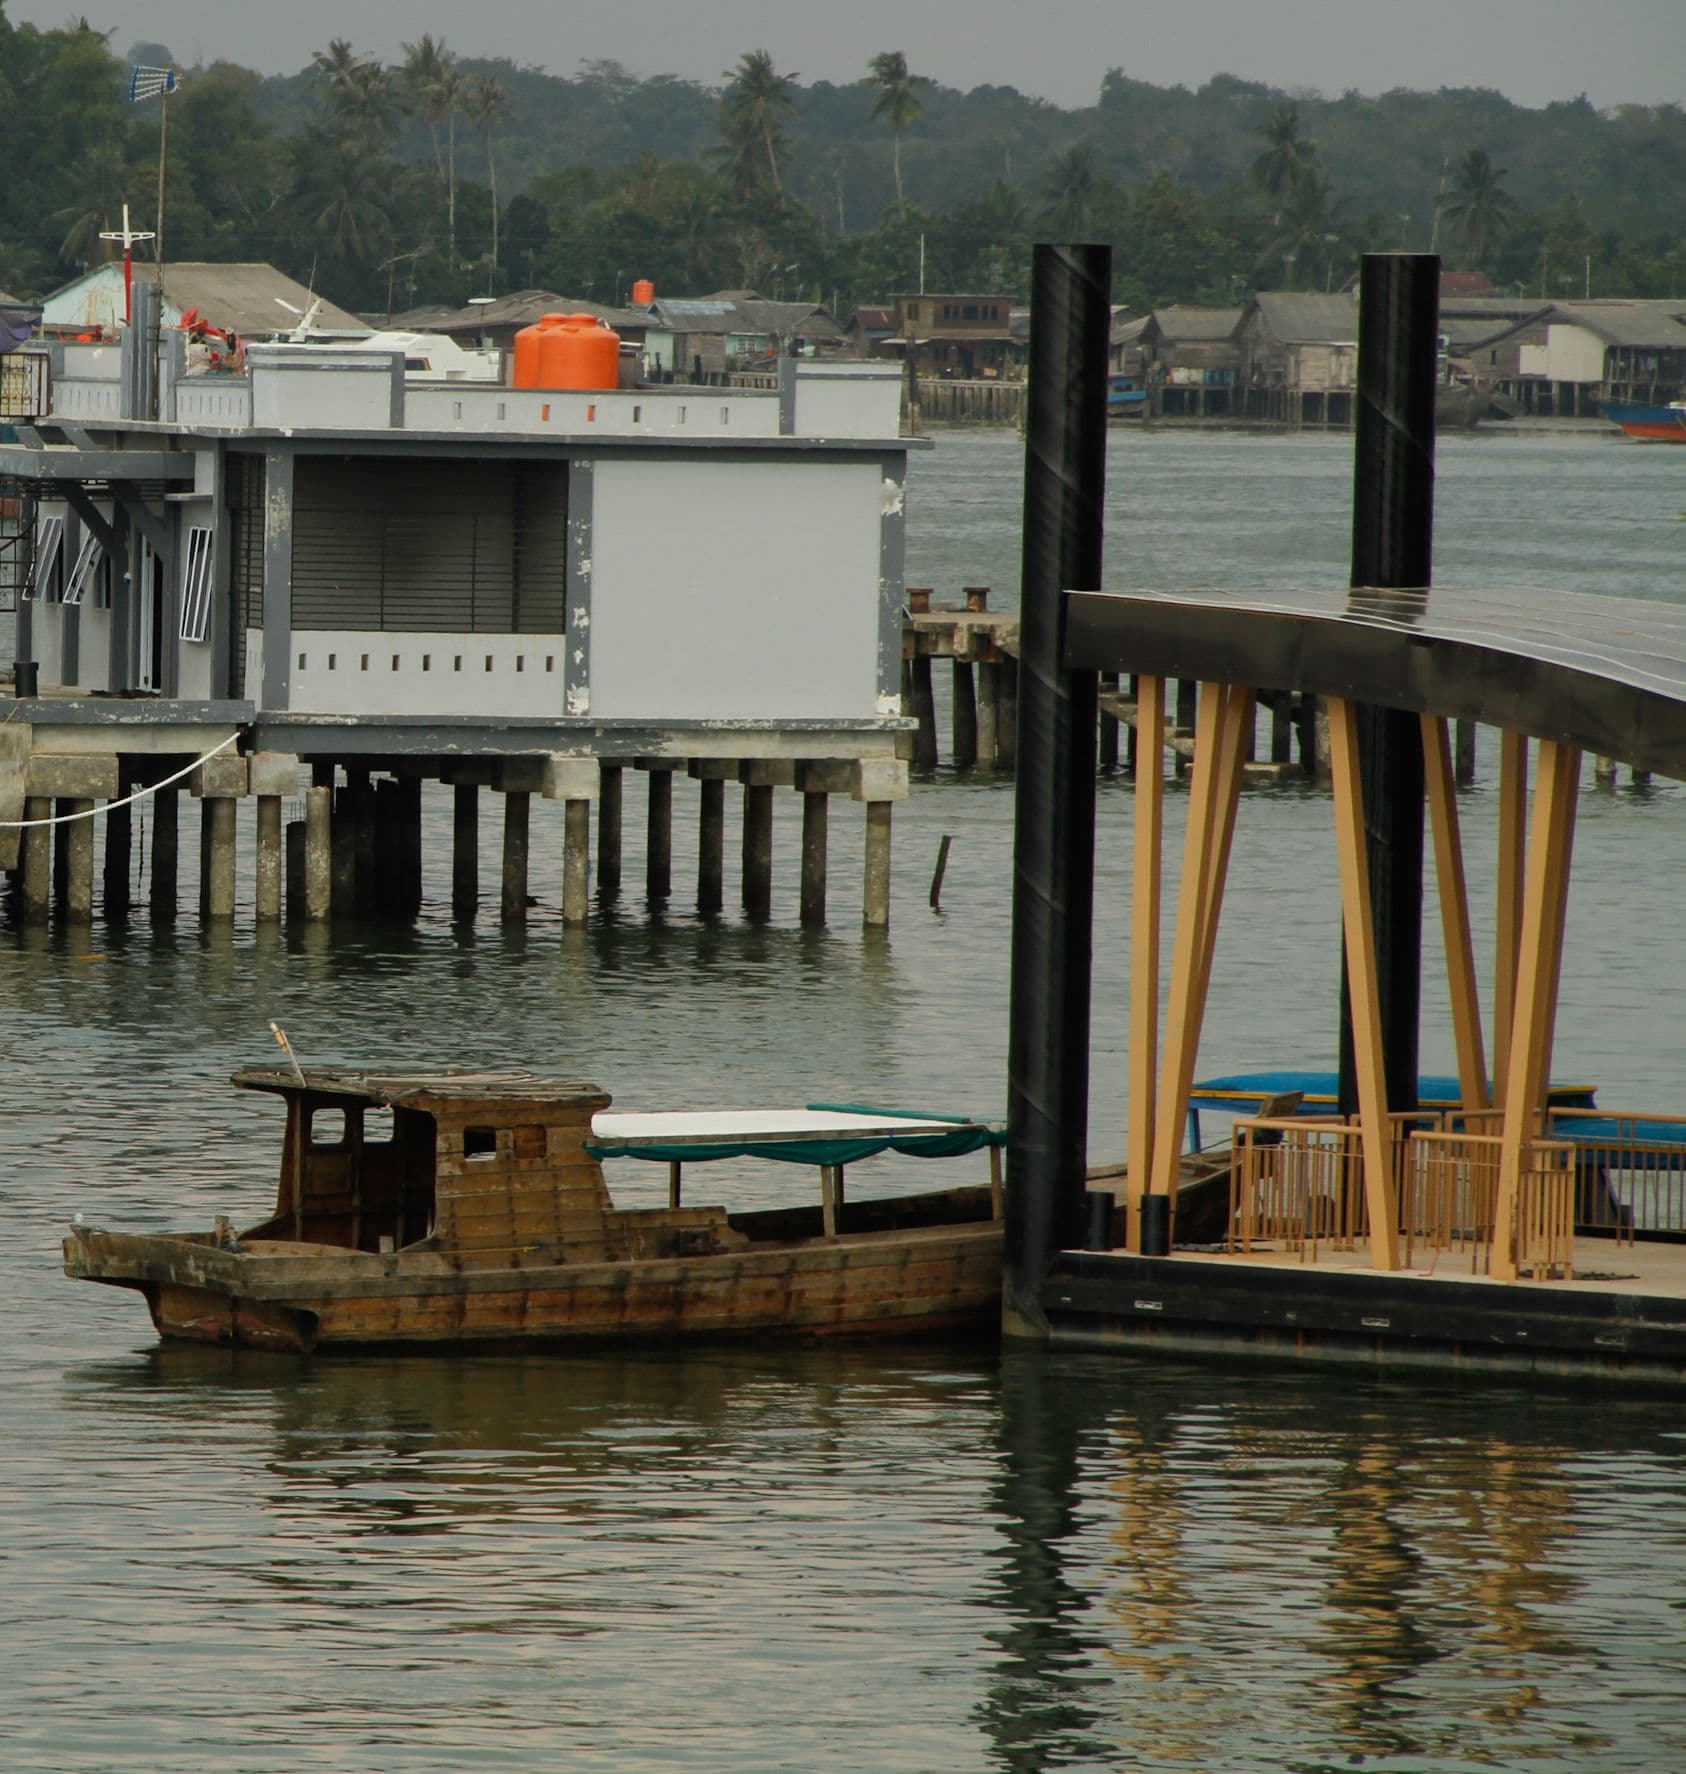
Risk oversight spans all three dimensions. Governance encompasses board and senior management oversight of risk frameworks, policies, and risk appetite. Planning and Development covers risk assessment for new port developments, climate resilience design, and continuity infrastructure. Operations includes day to day risk management, incident reporting, and emergency response.
Summary
Risk oversight is a foundational governance aspect of green port management, encompassing the systematic identification, assessment, management, and monitoring of risks across port operations, infrastructure, finances, safety, and sustainability (IAPH, 2023).
For ports across Asian Development Bank (ADB) Developing Member Countries (DMCs), strong risk oversight is particularly significant given the exposure of many DMCs to climate hazards, including tropical cyclones, flooding, sea level rise and extreme heat, alongside other natural hazards including earthquakes, and the complexity of managing operational, financial, and sustainability related risks in fast growing port environments (ADB, 2025).
Internationally, port risk management is shaped by frameworks including ISO 31000:2018 Risk Management Guidelines (ISO, 2018), ISO 14001:2026 Environmental Management Systems (ISO, 2026), and ISO 45001:2018 Occupational Health and Safety Management Systems (ISO, 2018b).
Climate related financial risk disclosure is guided by the Task Force on Climate related Financial Disclosures (TCFD) recommendations (Financial Stability Board, 2017) and the IFRS Sustainability Disclosure Standards IFRS S1 and IFRS S2 issued by the International Sustainability Standards Board (ISSB) in June 2023 (IFRS Foundation, 2023).
Nature-related disclosure is informed by the Taskforce on Nature related Financial Disclosures (TNFD) recommendations (TNFD, 2023).
In Southeast Asia, adoption of ISSB aligned climate disclosure requirements is progressing. In
- Singapore, the Accounting and Corporate Regulatory Authority (ACRA) and SGX RegCo require all listed issuers to report Scope 1 and 2 emissions from financial year 2025, with other ISSB based climate disclosures phased in between financial years 2025 and 2030 depending on issuer size, while requirements for large non listed companies have been deferred to financial year 2030 (ACRA, 2025).
- The Philippines has adopted IFRS S1 and S2 as PFRS S1 and PFRS S2, which the Securities and Exchange Commission has made mandatory for listed companies and large non listed companies in phases, starting with reports on 2026 data for the largest listed companies (SEC Philippines, 2025).
- Malaysia requires ISSB based reporting for large Main Market listed issuers from 2025 under its National Sustainability Reporting Framework (Securities Commission Malaysia, 2024),
- Indonesia has issued ISSB based standards PSPK 1 and PSPK 2 effective 1 January 2027 (IAI, 2025), and
- Thailand's SEC has announced approved principles for phased ISSB-aligned reporting, starting with SET50 index constituents, with the implementing regulations being amended (SEC Thailand, 2025).
The International Association of Ports and Harbors (IAPH) Risk and Resilience Guidelines for Ports, published in 2023, provide a sector specific framework to help ports establish a structured approach to risk management, business continuity, and organizational preparedness (IAPH, 2023).
Climate and natural hazard risks are particularly material for DMC ports. Research published in Communications Earth & Environment estimates that multi hazard risk to global port infrastructure, including asset damages and associated logistics losses, totals about USD 7.5 billion per year, with ports in lower middle income countries facing the highest risk relative to their size (Verschuur et al., 2023).
Peer reviewed research in Earth's Future has evaluated adaptation actions implemented at 13 major United Kingdom ports, finding that most documented actions respond to storms, flooding, and sea level rise, and that adaptation remains largely incremental rather than transformational (Jenkins et al., 2025).
A flood risk assessment of the Port of Rotterdam's unembanked areas under the EU ENHANCE project estimated expected annual direct losses of about EUR 5.8 million in 2015, rising to up to EUR 67 million per year by 2100, and provides a reference model for quantitative climate risk assessment in ports (ENHANCE Project, n.d.).
Effective risk oversight in ports encompasses several complementary practices: implementing an enterprise risk management (ERM) framework, establishing board and senior management risk governance, conducting climate and natural hazard risk assessments, maintaining business continuity and resilience plans, and operating systematic incident reporting and lessons learned processes. These practices collectively support port authorities' ability to anticipate and prepare for disruptions, protect workers and communities, maintain investor and lender confidence, and comply with emerging sustainability disclosure requirements.
In Southeast Asia, Westports Holdings Berhad, a terminal operator at Port Klang in Malaysia, published a Climate Change Assessment Report in 2022 that evaluates projected climatic changes to 2080 and the initial vulnerability of its port infrastructure (Westports, 2022).
PSA International has aligned its climate risk reporting with the TCFD recommendations, providing a reference for DMC port operators pursuing climate related financial disclosure (PSA International, 2023).
The Port Authority of Thailand plans to convert its five ports into smart and green ports by 2030 (International Trade Administration, 2024) and describes its strategy as transforming the authority into a resilient smart hub, with business and operational continuity among its priorities (Port Authority of Thailand, 2025).
Strong risk oversight provides the governance foundation for all other green port practices by ensuring that environmental, safety, operational, and climate related risks are systematically identified, managed, and disclosed (ADB, 2025; United Nations, 2015).
This aspect contributes to United Nations Sustainable Development Goal (SDG) 9 (Industry, Innovation and Infrastructure), SDG 11 (Sustainable Cities and Communities), SDG 13 (Climate Action), and SDG 16 (Peace, Justice and Strong Institutions).